
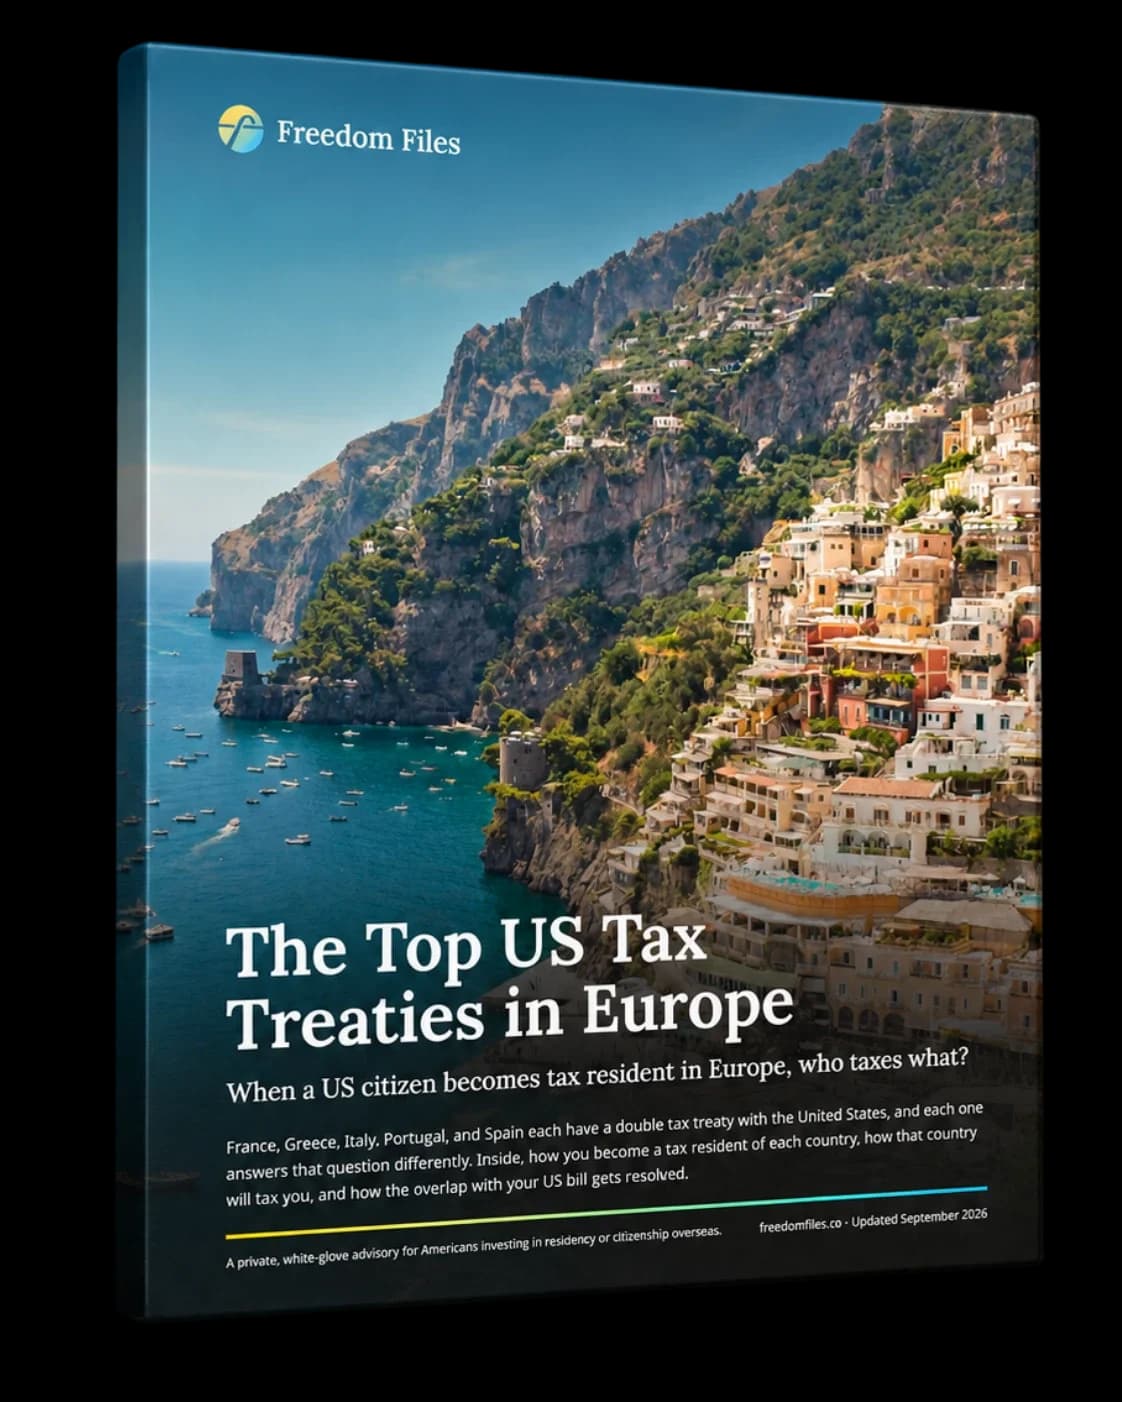
Live in These 5 High-Tax European Countries and Pay Little Tax
France, Greece, Italy, Portugal, and Spain each have a tax treaty with the United States, and each answers this question differently: When you become tax resident in Europe, who taxes what? Learn how that country will tax you if you move there and how the overlap with your US taxes gets resolved.
- The high-tax country where your IRA, 401(k), and Social Security are taxed only in the US, and your US dividends can cost you nothing locally.
- The August 2026 court ruling that decided one slice of your US bill can't be credited away under any treaty.
- Why a €100,000 flat tax that looks like a bargain makes an American pay twice on the same income.
- The government pension that's exempt in Spain until the day you take the passport.
This guide does not constitute tax, financial, or legal advice. Consult the Freedom Files' licensed tax professional partners before considering action.
- 200+ families served
- 53 programs in 6 continents
- 10+ years in practice
- 200K+ educated monthly
This guide could save you thousands, if not millions
The treaty, the regime, and the filing are all decided early, most of them in your first year of residence. Get one wrong and the cost compounds every year you live abroad. A few of the numbers inside:
Greece
€1.5M
What an American pays Athens over 15 years on the €100,000 lump sum, on top of a full US bill, with no credit either way. Under the 7% regime the Greek bill on that income often comes to nothing.
France
€0
The French tax on your US dividends and interest once the Article 24 credit is claimed. Miss that line on the annual French return and the whole benefit is gone.
Italy
7% vs 43%
The southern flat tax against Italy's top ordinary rate. The choice gets made in your first year of residence, and the town you pick decides it.
Portugal
40%+
The effective rate retirement income can reach now that NHR is closed. Whether your work fits the IFICI list changes everything downstream.
Spain
€1,000s
What the Social Security dispute is worth on a $60,000 benefit, every year you live there, unless your position is settled before the first return.
Every one of these is decided before your first European tax return. The guide shows you which ones apply to you.
What's inside
5 treaties compared on 15 measures
Every treaty gets its own page: How you become a tax resident, how that country will tax you, and how the overlap with your US bill gets resolved. Each page ends with our read on who the treaty favors and where it catches Americans off guard. The last page puts all five side by side.
The Convention of 1994
France
Your US pensions and Social Security are taxed only in the US, and a credit cancels the French tax on your US portfolio income.
Learn more →
The Convention of 1950
Greece
The oldest US tax treaty in force anywhere. The 7% regime does the work a modern treaty would do.
Learn more →
The Convention of 1999
Italy
A modern treaty that sends your Social Security to Rome, and a 7% regime that grants no credit for your US tax.
Learn more →
The Convention of 1994
Portugal
With NHR closed, this 30-year-old text now decides the retiree's bill, and pension income can face rates past 40%.
Learn more →
The Convention of 1990
Spain
The most current of the five, and the most argued question in Europe: Who gets to tax your Social Security.
Learn more →
Compare all 5 treaties side by side
15 measures, from where your pension is taxed to who recognizes your Roth.
See the preview →
“France reads like a high-tax country and behaves like a low-tax one for the right American.”
A preview of the comparison
When you move, who taxes what?
4 of the 15 measures from the guide's closing page. The older the convention, the less it protects you, and in 4 of these 5 countries the rate on your return comes from domestic law layered above the treaty.
| Measure | France | Greece | Italy | Portugal | Spain |
|---|---|---|---|---|---|
| Convention in force | 1995 | 1953 | 2010 | 1996 | 1990 |
| Private pension, IRA, 401(k) | United States | Greece | Italy | Portugal | Spain |
| US Social Security | United States | Greece | Italy | Both, with credit | Disputed |
| Roth distributions | Preserved | Not recognized | Not recognized | Not recognized | Not recognized |
11 more measures in the guide, including US government pensions, re-sourcing, wealth taxes, and foreign-asset reporting.
Who this is for
Written for Americans, not for everyone
The US taxes its citizens on worldwide income wherever they live, so for an American the treaty isn't a footnote. It decides which country taxes your pension, your Social Security, and your brokerage account, and whether the credit between the two bills works in your favor. Every page of this guide is read through that lens. Your own result depends on your income mix, your state of residence, and the year you become a tax resident.
Frequently asked questions
Will I pay tax twice if I move to Europe?
Not on the same dollar. Each treaty gives one country the first right to tax a type of income and gives the other a credit, so you pay the higher of the two bills, not both. The exceptions are in the guide: A Greek lump sum stacks on your US bill, and a 2026 federal ruling says French tax can't offset the 3.8% Net Investment Income Tax.
Where are my IRA, 401(k), and private pension taxed?
In France, only in the United States. In Greece, Italy, Portugal, and Spain, the country you live in takes the first right to tax them, and your US foreign tax credit handles the overlap.
Who taxes my US Social Security?
France leaves it to the United States. Greece and Italy tax it as your country of residence. Portugal and the US both tax it, with a credit. Spain is disputed: The Spanish tax agency taxes it with a credit, and several respected firms read the treaty the other way.
Is my Roth IRA tax-free in Europe?
Only in France, where a qualified Roth distribution reaches you untaxed on both sides. Greece, Italy, Portugal, and Spain don't recognize the Roth, so plan as though the distribution is taxed locally.
What about a federal, military, or foreign-service pension?
France, Italy, and Portugal leave it to the United States alone. Spain exempts it until you naturalize, so model the citizenship path first. Greece's 1950 treaty complicates it, so confirm your position in writing before you move.
Do special tax regimes override these treaties?
In 4 of the 5 countries, the rate on your return comes from domestic law layered above the treaty: Greece's 7% regime, Italy's southern 7% and lump sum, Portugal's IFICI, and Spain's Beckham regime. Some help an American and some cost one, because Italy's 7% and Greece's lump sum grant no credit for your US tax. France needs no regime at all.
How do I become a tax resident in each country?
Mostly by spending 183 days there, with local twists. In France any single test is enough: Your home, your main work, or your center of economic interests. In Greece a Golden Visa on its own doesn't make you tax resident.
How current is the guide?
Every treaty article, rate, and threshold is current to September 2026. Treaties change slowly, but the domestic regimes above them change often, so verify figures against official sources before you act.
Get the guide before your first European tax return
Most of these decisions get locked in during your first year of residence, and the wrong one can cost an American €1.5 million in Greece alone. The treaties change slowly. The regimes layered above them don't: Italy's lump sum has tripled since it launched, and Portugal closed NHR to new applicants in 2025. Every figure in this guide is current to September 2026. Enter your name and email and the PDF arrives in your inbox in under a minute.
Nu Age Ventures, LLC dba Freedom Files does not provide tax, legal, investment, accounting, or financial advice. Educational content only. Verify all figures with licensed counsel before acting.
About the publisher
Who created this
The Freedom Files is a private advisory for American families building optionality outside the US. Its founder James Nuveen left the US a decade ago, has lived in more than 15 countries, and has multiple residencies and citizenships of his own. Engagements are senior-led and delivered with vetted local legal, tax, and government partners.
This guide is not financial or tax advice. It's for informational purposes only. Verify every figure with licensed counsel before acting.